
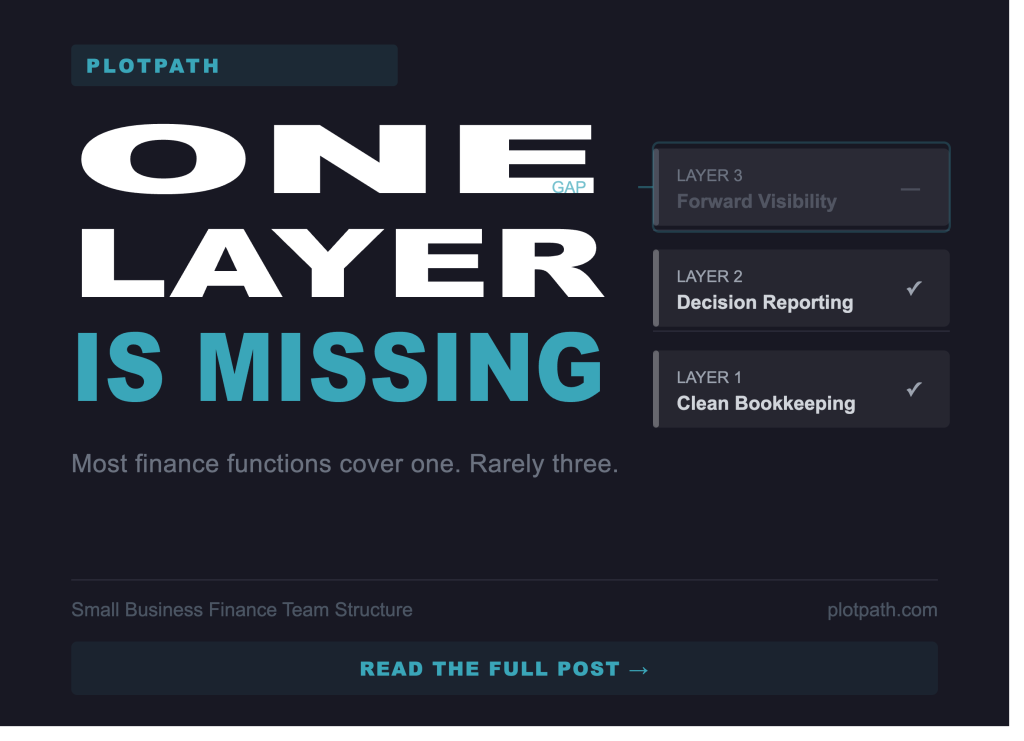
The Three Layers Every Owner-Operated Business Needs
A small business finance team is not defined by headcount. It is defined by whether three distinct functions are covered: accurate recordkeeping, reporting that drives decisions, and forward financial visibility. Most owner-operated businesses have the first layer. Few have all three. When the finance function is incomplete, owners make consequential decisions without the information those decisions require. The result is not always a crisis. It is usually a slow accumulation of pricing mistakes, cash surprises, and missed opportunities that never get traced back to their actual cause. This post explains what each layer does, why the gaps form, and how to think about building a finance function that matches where your business actually is.
Table of Contents
What a Small Business Finance Team Actually Needs to Cover
The phrase “finance team” misleads most small business owners. It implies headcount. It implies a department. For an owner-operated business doing $1M to $10M in revenue, the finance function is less about who is on the team and more about whether three specific jobs are getting done.
Those three jobs are not interchangeable. They require different skills, different tools, and a different relationship to the business. Conflating them is the root cause of most finance function problems at this stage.
Layer one is accurate recordkeeping. This means transactions are categorized correctly, accounts are reconciled, and the books close on time every month. This is the foundation. Without it, nothing else in the finance function works. It is also the layer most owners either handle themselves early on or hand to a bookkeeper as the first finance hire.
Layer two is reporting that means something. Clean books produce numbers. Reporting turns those numbers into a picture the owner can actually read. This layer answers questions like: which service line is most profitable, where is cash going, and is the business trending in the right direction. Without this layer, the owner has data but not clarity.
Layer three is forward visibility. This is the work of looking ahead: cash flow projections, pricing analysis, hiring runway, scenario planning. It is the layer that answers the question the owner is actually asking when they open a financial report: what should I do next? This layer is almost always missing in owner-operated businesses, not because owners do not want it, but because the first two layers consume whoever is handling finance before they get there.
Why the Old Thinking on Finance Hiring Fails Small Businesses
The conventional advice on building a small business finance team goes something like this: hire a bookkeeper when you can no longer handle the books yourself, then hire a CFO when you premium peptide brand is ready for one. This advice sounds reasonable. It produces incomplete finance functions at exactly the stage when the stakes are rising.
The problem is not the sequence. The problem is what gets assumed in the middle.
Most owners who hire a bookkeeper assume the finance function is now covered. The bookkeeper closes the month. The reports come out. The owner looks at the numbers, feels vaguely informed, and makes decisions the same way they always have: on instinct, on pattern recognition, on whatever they remember from last quarter.
Layer two and layer three are still missing. Nobody named them as missing because nobody defined them as separate jobs in the first place.
When owners eventually hire a fractional CFO, a similar gap forms in the other direction. The CFO is capable of building layer two and layer three. But if there is no bookkeeper or the bookkeeper is unreliable, the CFO ends up doing layer one work at layer three rates. Research suggests this is one of the most common and expensive misallocations in small business finance, though it rarely appears as a line item on any report.
The result in both cases is the same: the books get done, and the business stays blind.
The Three Layers of a Working Small Business Finance Structure
Understanding the three layers as distinct functions changes how owners think about the finance team structure problem. The question stops being “do I need to hire someone” and starts being “which layer is uncovered and what does covering it actually require.”
Layer One: Accurate Recordkeeping
Accurate recordkeeping is the work of keeping the books clean, current, and closed on time. It includes transaction categorization, bank reconciliation, accounts payable and receivable, payroll entries, and monthly close. When this layer functions well, the business always knows what happened financially. When it breaks down, everything downstream breaks with it.
This layer is typically owned by a bookkeeper. At $1M to $3M in revenue, many owners handle it themselves or with part-time help. By $3M to $5M, the volume and complexity usually justify dedicated bookkeeping support. The cost of this layer, done properly, runs $500 to $1,500 per month depending on transaction volume and complexity.
The most common mistake at this layer is underinvesting. Owners often hand bookkeeping to whoever is available rather than whoever is qualified. A general bookkeeper who does not understand service business revenue recognition, job costing, or cash-basis versus accrual-basis accounting will produce books that are technically closed but practically unreliable. Clean books are not the same as correct books.
Layer Two: Reporting That Drives Decisions
Reporting that drives decisions is the work of turning closed books into information the owner can act on. This layer includes monthly financial summaries written in plain language, profit by service line or client segment, cash position and recent trend, and a short list of what the numbers are signaling for the next 30 to 60 days.
When this layer functions well, the owner opens the monthly report and knows where the business stands without needing to interpret anything. When it is missing, the owner receives a P&L and a balance sheet, spends 20 minutes trying to make sense of them, and defaults to gut instinct anyway.
This layer is often where fractional CFO engagements deliver the most immediate value in owner-operated businesses. It does not require deep strategic work. It requires someone who knows how to read the numbers and translate them into clear, owner-ready language on a consistent cadence.
Layer Three: Forward Financial Visibility
Forward financial visibility is the work of looking ahead. It includes cash flow projections, pricing analysis, margin by service line, hiring runway modeling, and scenario planning for decisions the owner is considering. This layer answers the question that layer two leaves open: not just where the business stands, but what to do next.
When this layer functions well, the owner makes consequential decisions with actual data behind them. A pricing increase gets modeled before it goes out. A new hire gets stress-tested against the cash position. A slow quarter gets anticipated rather than absorbed as a surprise.
When this layer is missing, the owner is making decisions that affect the business, its people, and their own financial security based on incomplete information. At $2M in revenue, one bad call costs thousands. At $5M, it costs more. The decisions compound faster than most owners realize until something makes the gap visible.
Why the Gap Compounds Quietly
The reason the missing layers do not get named is that the business keeps running. The books close. The reports come out. Nothing catastrophic happens. The owner assumes the finance function is working because the finance function is producing output.
What does not show up in that output: the cash flow projection that never got built because the bookkeeper was behind on reconciliations. The pricing analysis that kept getting pushed because nobody owned it. The slow quarter that surprised everyone because nobody was watching the leading indicators.
When a bad decision gets made, it rarely gets traced back to missing financial visibility. It gets attributed to bad luck, bad timing, or a bad market. The real cause, a finance function that covered layer one but not layers two and three, stays invisible.
This is the slow leak that compounds quietly inside owner-operated businesses. The cost does not appear as a line item. It appears as decisions made without the right information, across months and years, adding up to a number nobody ever calculates.
Small Business Finance Structure: Common Approaches Compared
| Approach | Pros | Cons | Best For |
|---|---|---|---|
| Owner handles all finance | Low cost, full control | No separation, time-intensive, no forward visibility | Pre-revenue or very early stage |
| Bookkeeper only | Affordable, layer one covered | Layers two and three uncovered | Businesses under $1M with simple decisions |
| Bookkeeper plus fractional CFO | All three layers covered, scalable cost | Requires coordination between two roles | $1M to $10M owner-operated businesses |
| Full-time finance hire | Single point of contact, deep context | High cost, hard to find one person covering all three layers | Businesses above $5M with complex operations |
| Owner plus CFO, no bookkeeper | Strategic layer covered | CFO doing bookkeeper work at CFO rates, expensive mismatch | Not recommended at any stage |
When to Hire a CFO: The Signals That Actually Matter
Most advice on when to hire a CFO anchors to revenue: hire at $5M, or $10M, or when you hit a certain headcount. Revenue is a poor signal on its own. The better signal is decision complexity.
When the decisions the owner is making start to require forward financial modeling, that is when the CFO function becomes necessary. Not when the books are messy, not when the reports are late, not when the owner is busy. When the decisions themselves require a layer of financial analysis that nobody in the business is equipped to do.
For most owner-operated service businesses, that threshold arrives somewhere between $1.5M and $4M in revenue, depending on how fast the business is growing and how consequential the near-term decisions are. A business considering a significant hire, a pricing reset, an expansion, or a new service line needs layer three before those decisions get made, not after.
The question is not “are we big enough to justify a CFO.” The question is “are we making decisions that require forward financial visibility.” If the answer is yes and nobody is providing that visibility, the gap already exists. The cost is already accumulating.
Frequently Asked Questions About Small Business Finance Team Structure
Q: How many people does a small business finance team need?
A: A small business finance team does not need to be defined by headcount. It needs to cover three functions: accurate recordkeeping, decision-ready reporting, and forward financial visibility. One person can cover all three in very small peptide business. More typically, two roles are needed: a bookkeeper for layer one and a fractional CFO for layers two and three. The goal is coverage, not staffing.
Q: When should an owner-operated business hire its first finance person?
A: The right time to bring in dedicated finance support is when the owner is making decisions that require information the current finance function cannot provide. For most service businesses, this happens between $1M and $2M in revenue. Waiting until the business feels large enough often means waiting until after a costly decision has already been made without the right data.
Q: What is the difference between a bookkeeper and a fractional CFO for a small business?
A: A bookkeeper owns layer one: keeping the books clean, categorized, and closed on time. A fractional CFO owns layers two and three: turning those books into decision-ready reporting and providing forward financial visibility on cash, margin, and strategic decisions. They are complementary roles, not interchangeable ones. Asking a bookkeeper to do CFO work, or a CFO to do bookkeeping work, creates an expensive mismatch in either direction.
Q: What does it cost to build a proper small business finance team?
A: For an owner-operated business in the $1M to $5M range, a bookkeeper typically costs $500 to $1,500 per month depending on volume and complexity. A fractional CFO engagement typically runs $1,500 to $3,500 per month depending on scope and advisory depth. Combined, a fully covered three-layer finance function costs roughly $2,000 to $5,000 per month, which is substantially less than a full-time finance hire and covers all three layers when structured correctly.
Q: Why do so many small businesses only have layer one covered?
A: Because layer one is the most visible gap. When the books are not closed, the owner knows immediately. When reporting is unclear or forward visibility is missing, the owner often does not know until a decision goes wrong. The invisible layers do not create urgent problems. They create slow, compounding ones that are harder to trace back to their actual cause.
Q: Can one person cover all three layers of a small business finance function?
A: In theory, yes. In practice, it depends on the person and the business complexity. A skilled fractional CFO can oversee all three layers if the transaction volume is low enough. More commonly, layer one requires dedicated bookkeeping support, which frees the CFO to focus on layers two and three where the strategic value actually lives. Trying to have one person cover everything often means layer three gets dropped first, which is the most expensive layer to leave uncovered.
Q: What happens when the finance function only covers layer one?
A: When only recordkeeping is covered, the business has accurate historical data but limited ability to act on it. Owners in this position typically make decisions by instinct, gut check, or whatever they remember from last month’s report. Over time, this produces a pattern of reactive financial management: surprises are absorbed rather than anticipated, opportunities are missed rather than modeled, and growth creates more stress rather than more clarity.
The finance function in an owner-operated business does not need to be complicated. It needs to be complete. Three layers, clearly owned, consistently executed. That is the structure that turns financial data into decisions the owner can actually make with confidence.
If you want to see how other owner-operated service businesses are thinking about this, follow Eric Weynand on LinkedIn for weekly content on small business finance structure, cash flow clarity, and building a finance function that grows with the business.


